Want waterfront living within reach of Richmond? Chesdin Landing on Lake Chesdin is one of the best options in the region. I toured it to show you what around $1 million buys on the water.
The lake...
Veterans · Active Duty · Guard · Reserve · Surviving Spouses
VA Loan Home Buying in Richmond & the Fort Lee Area
$0 down, no PMI, and a team led by a 25-year Army veteran who knows PCS timelines, TDY trade-offs and Guard and Reserve eligibility.
#2 Mega Team in Richmond (RealTrends Verified 2026) · 5.0★ Zillow, 46 reviews · eXp ICON Award 2026
The short answer
How VA home buying works in Richmond and the Fort Lee area
Eligible veterans, active-duty service members, National Guard and Reserve members, and some surviving spouses can buy a primary home in Virginia with $0 down and no monthly mortgage insurance using a VA-guaranteed loan. Most first-time users putting less than 5% down pay a one-time 2.15% VA funding fee, and veterans who receive VA disability compensation pay no funding fee. One Dream Realty Group, led by 25-year U.S. Army veteran Dustin Olverson, helps military buyers in Richmond, Chesterfield, Petersburg, Prince George and the Fort Lee area use the benefit without surprises.
$0down payment for eligible buyers with full entitlement
$0monthly PMI, ever
2.15%funding fee, first use, under 5% down
0%funding fee if you receive VA disability pay
4%max seller concessions (plus normal closing costs)
Start with your situation
Pick the path that fits you
Veterans & retireesEligibility, reusing your benefit, Virginia tax breaks Active duty on PCS ordersBuying before you report, BAH, breaking a lease TDY & schools at Fort LeeWhen to rent, when buying makes sense National Guard6-year and Title 10 / Title 32 eligibility ReserveSelected Reserve eligibility and documents Surviving spousesDIC, funding fee exemption, property tax relief
Veterans & military retirees
Using your VA loan after you get out
If you served on or after August 2, 1990, you generally qualify with 24 continuous months of active duty, or the full period you were called to active duty (at least 90 days). Shorter service can still qualify if you were discharged for a service-connected disability or another VA-approved reason. Your lender can usually pull your Certificate of Eligibility (COE) online in minutes.
- You can use it again. The VA loan is not one-and-done. Once a VA loan is paid off (for example, when you sell), your entitlement can be restored. Using it a second time raises the funding fee to 3.3% with less than 5% down, unless you are exempt.
- No VA loan limit with full entitlement. If you have full entitlement, VA does not cap the loan amount. Your lender sets the limit based on income, credit and the appraisal. If part of your entitlement is still tied up in another home, county loan limits apply.
- Virginia retirement tax break. Starting with tax year 2025, Virginia lets you subtract up to $40,000 of military retirement income from state taxable income, with no age requirement (Va. Code § 58.1-322.02).
- 100% P&T disabled? Your home can be property-tax free. Virginia exempts the primary home and up to one acre of a veteran rated 100% service-connected, permanent and total (Va. Code § 58.1-3219.5). You can file with your locality's Commissioner of the Revenue before you buy, and it applies once you own.
Takeaway: Get your COE and a pre-approval first, then ask your lender to show you the funding fee in dollars. If you have a disability rating, make sure it is on your COE so the fee is waived.
Active duty · PCS
PCSing to Fort Lee, DSCR or the Richmond area
Active-duty service members qualify after 90 continuous days of service. The hard part of a PCS purchase isn't the loan. It's the clock. Here's how we keep your closing tied to your report date:
- As soon as you have orders: get pre-approved and send us your report date, BAH rate, commute limit and school needs. Use the DoD BAH calculator for your new duty station.
- Tour from where you are: we do live video walkthroughs and answer your questions about the street, the commute and resale.
- Ask your command about house hunting: the services can authorize permissive TDY for house hunting tied to a PCS. Rules and days vary by service, so confirm with your unit.
- Close on your timeline: we line up inspection, VA appraisal and closing to land near your arrival, including mail-away or power-of-attorney signing when your lender and settlement company allow it.
- Occupancy rule: VA expects you to move in within a reasonable time, usually 60 days. Your spouse can satisfy occupancy if you're deployed or not there yet.
- Breaking a lease: the Servicemembers Civil Relief Act lets you end a residential lease for PCS orders or a deployment of 90+ days. You give written notice and a copy of your orders. For monthly rent, it ends 30 days after the next rent due date (50 U.S.C. § 3955).
- Plan for your next PCS now: many service members keep the home as a rental after they move. Pick a house and neighborhood that rent well, and we'll show you the rent numbers before you offer.
Takeaway: Start 60 to 90 days before your report date. Compare the full monthly payment (principal, interest, taxes and insurance) to your BAH, not just the price.
TDY & schoolhouse
Here on TDY or at school at Fort Lee
Fort Lee is home to the Combined Arms Support Command (CASCOM), the Quartermaster, Ordnance and Transportation schools, and Army Sustainment University, so many soldiers come through on TDY. A VA loan has to be for your primary residence, so a short TDY alone usually isn't a reason to buy here.
- Rent for the TDY if you'll be back at your home station in weeks or months.
- Buying can make sense if your family lives here, you're expecting PCS orders to the area, or you're retiring here and want to scout neighborhoods while you're on the ground.
- Use the time well: drive the commutes at rush hour, visit schools, and meet us for a no-pressure tour so you're ready when orders come.
Takeaway: Call us for a straight answer on rent vs. buy for your situation. Sometimes the right answer is "not yet."
National Guard
VA loans for National Guard members
Guard members qualify with any one of these:
- 6 creditable years in the Guard, and you're still serving or were honorably discharged or retired.
- 90 days of non-training Title 10 active duty.
- 90 days of Title 32 full-time duty (including 30 consecutive days) under 32 U.S.C. 316, 502, 503, 504 or 505, shown on your DD-214.
Guard and Reserve members pay the same funding fee as active duty and veterans. Virginia also lets eligible Guard members (O-6 and below) subtract up to $5,500 of Guard pay from state taxable income. If you drill at Fort Pickett near Blackstone, Chesterfield, Dinwiddie and Petersburg put you within reach of both drill and Richmond-area jobs.
Takeaway: Have your statement of service or points statement (or DD-214 for activations) ready. Lenders who don't do many Guard loans get stuck here, so ask your lender how many they've closed.
Reserve
VA loans for Reserve members
Reservists qualify with 6 creditable years in the Selected Reserve (still serving, honorably discharged or retired), or 90 days of non-training active duty. Mobilizations count, so check your DD-214s from any activations.
Takeaway: Request your retirement points statement early. It's the document most often missing when Reserve buyers apply for a COE.
Surviving spouses
Surviving spouses can use the benefit too
- Eligibility: you may qualify if you receive or are eligible for Dependency and Indemnity Compensation (DIC), or if your spouse is missing in action or a prisoner of war.
- No funding fee if you receive DIC.
- Property tax relief in Virginia: the surviving spouse of a veteran rated 100% P&T can keep the real estate tax exemption on a primary residence as long as they don't remarry, even after moving. Virginia also has a separate exemption for surviving spouses of service members killed in action.
Takeaway: Bring your DIC award letter to your lender and your locality's Commissioner of the Revenue. We'll help you find the right office for the county you buy in.
The process
The VA home-buying process, step by step
- Get your COE and pre-approval. We'll connect you with lenders who close VA loans regularly. Shop at least two. Rates and lender fees vary.
- Strategy call with us. Budget vs. BAH or income, commute, schools, and resale or rental value for your next move.
- Tour in person or by live video. We flag homes likely to have VA appraisal issues (peeling paint on older homes, roof, heat, safety) before you fall in love with them.
- Write a strong offer. VA allows seller concessions up to 4% of the price, plus normal closing costs. VA rules on buyer-broker fees changed in 2024 (VA Circular 26-24-14). We explain exactly how our compensation is handled, and ask the seller to cover it where possible, before you sign anything.
- VA appraisal. The appraiser checks value and VA's Minimum Property Requirements. If the value looks low, VA's "Tidewater" process gives us a chance to send the appraiser more sales data before the report is final.
- Home inspection. A VA appraisal is not an inspection. Always get your own.
- Close and move in. Usually 30 to 45 days from contract, depending on the lender, appraisal and repairs.
Where military buyers live
Neighborhoods near Fort Lee, DSCR and the Richmond VA Medical Center
Near Fort Lee (Prince George County)
Prince George, Petersburg, Colonial Heights, Hopewell, Chester and Dinwiddie are the common picks for short commutes to Fort Lee.
Near Defense Supply Center Richmond
DSCR, home of DLA Aviation, sits in Chesterfield County off Route 1. Chester, North Chesterfield and Midlothian keep the drive short.
Near VA health care and Richmond jobs
The Richmond VA Medical Center (McGuire) is in South Richmond. Richmond, Henrico and Powhatan add more options for veterans working in the city.
Myths vs. facts
What other agents get wrong about VA loans
"Sellers won't take VA offers."
Many do when the offer is written well. We present your financing, appraisal plan and timeline so a VA offer looks as solid as conventional.
"You can only use it once."
You can use it again and again. Entitlement can be restored after the loan is paid off.
"There's a VA loan limit."
Not with full entitlement. Your lender decides how much you can borrow.
"You need perfect credit."
VA sets no minimum credit score. Lenders set their own, so it pays to shop.
"VA appraisals kill deals."
Most issues are predictable (paint, roof, heat, safety). We spot them at the showing, not after.
Free checklist
Military home-buyer document checklist
- Certificate of Eligibility (COE), or the documents to request it
- PCS orders and report date (active duty)
- Last 30 days of LES or pay stubs
- Two years of W-2s and tax returns
- Two months of bank statements
- DD-214 (veterans and activated Guard/Reserve)
- Statement of service or retirement points statement (Guard/Reserve)
- VA disability award letter (for the funding fee exemption)
- DIC award letter (surviving spouses)
- Power of attorney if a spouse or agent will sign for you
Who you'll work with
A veteran-led team that has done this move itself
"I served 25 years in the U.S. Army, including a deployment to Iraq as a sergeant on a convoy security team. I know what a PCS move feels like and what it's like to buy a home on a timeline you don't control. Our team includes other veterans and military-connected agents, and we built it to help military families use the benefit they earned." — Dustin Olverson
- #2 Mega Team in Richmond by sides & volume (RealTrends Verified 2026)
- eXp ICON Award 2026
- 5.0★ on Zillow (46 team reviews)
- Office: 717 N Courthouse Road, Suite 101, North Chesterfield, VA
Search Homes for VA Buyers
Richmond, Chesterfield, Henrico, Powhatan, Petersburg and Prince George
Browse every home for sale in the Richmond area. Tell us your must-haves and we will flag the homes that are likely to pass a VA appraisal.
Get pre-approved first so you know your buying power and sellers know you are ready.
Start Searching
Sign Up for Listing Alerts
Be the first to know when a new property hits the market
Listing Alerts give you the edge over others looking to buy – once you register for Listing Alerts, an email is delivered straight to your inbox the moment a new property that matches your wish list criteria hits the market, enabling you to act fast.
Get Set Up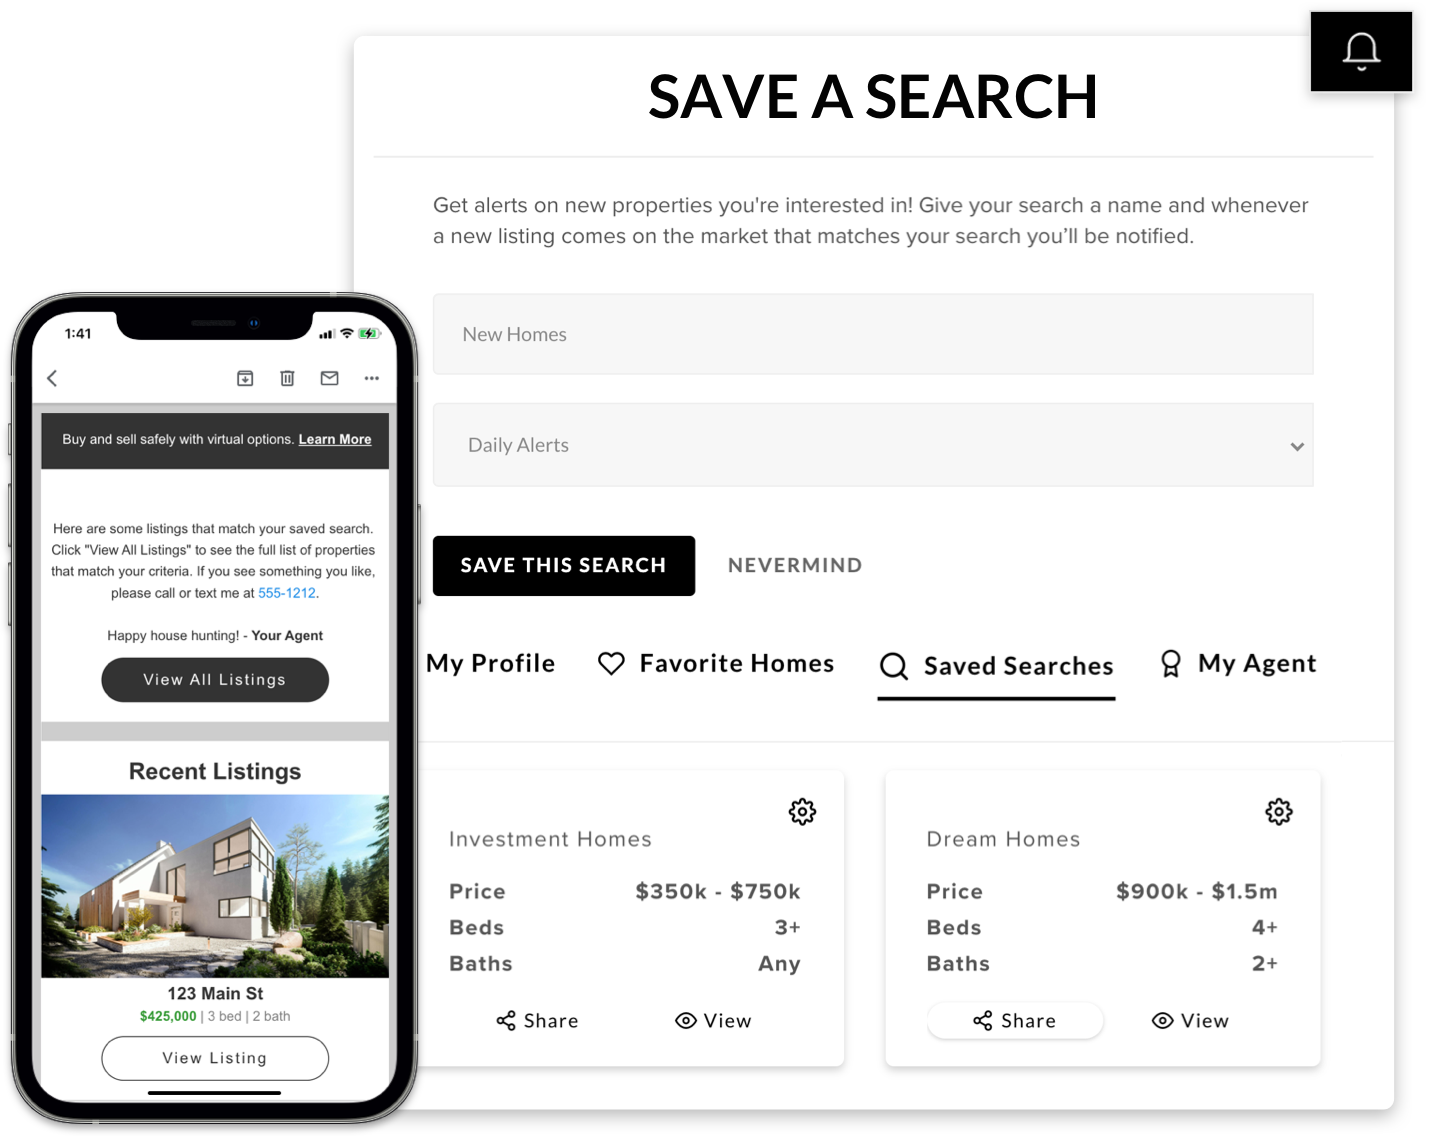
Ask a veteran
Have orders, a COE question or a deadline?
Talk to someone who has worn the uniform. No pressure and no obligation. Tell us your situation and we'll give you a straight answer, even if it's "rent for now."
FAQ
VA loan questions we hear every week
How much is the VA funding fee in 2026?
For a purchase, first-time use with less than 5% down is 2.15% of the loan amount; 5% down drops it to 1.5% and 10% down to 1.25%. After first use, it's 3.3% with less than 5% down. Veterans who receive VA disability compensation, surviving spouses receiving DIC, and active-duty Purple Heart recipients don't pay it. The fee can be rolled into the loan.
Can I use a VA loan if I'm in the National Guard or Reserve?
Yes. You qualify with 6 creditable years of service, or 90 days of non-training active duty. Guard members can also qualify with 90 days of Title 32 full-time duty, including 30 consecutive days, under 32 U.S.C. 316, 502, 503, 504 or 505.
Can I buy a home before I arrive on PCS orders?
Yes. With live video tours, you can be under contract before you report. VA expects you to occupy the home within a reasonable time, usually 60 days, and your spouse can satisfy occupancy if you are deployed or not there yet.
Should I buy a home while I'm TDY at Fort Lee?
Usually not for a short TDY. A VA loan must be for your primary residence. Buying can make sense if your family lives here, you're expecting PCS orders to the area, or you plan to retire here.
Can I break my lease if I get PCS orders?
Yes. Under the Servicemembers Civil Relief Act (50 U.S.C. § 3955), you can end a residential lease for PCS orders or a deployment of 90 days or more by giving written notice with a copy of your orders. For monthly rent, termination takes effect 30 days after the next rent due date.
Is there a VA loan limit in Virginia?
Not if you have full entitlement; your lender decides how much you can borrow. If some entitlement is still tied to another VA loan, the county conforming loan limit is used to figure your remaining entitlement, and a down payment may be needed above it.
Can I use my VA loan more than once?
Yes. Entitlement can be restored after a VA loan is paid off, such as when you sell. Subsequent use carries a higher funding fee (3.3% with less than 5% down) unless you're exempt.
Do disabled veterans pay property tax in Virginia?
Veterans rated 100% service-connected, permanent and total disabled are exempt from real estate tax on their primary home and up to one acre (Va. Code § 58.1-3219.5). A surviving spouse who doesn't remarry can keep the exemption. Apply with the Commissioner of the Revenue in the county or city where you buy.
Does Virginia tax military retirement pay?
Starting with tax year 2025, Virginia allows a subtraction of up to $40,000 of military retirement income, with no age requirement (Va. Code § 58.1-322.02).
Can the seller pay my closing costs on a VA loan?
Yes. Sellers can pay normal closing costs, plus concessions of up to 4% of the price, which can cover things like the funding fee or paying off debts to help you qualify.
What's the difference between a VA appraisal and a home inspection?
The VA appraisal checks value and VA's Minimum Property Requirements (safe, sound and sanitary). It is not a full inspection, so get your own home inspection too.
Where do military families live near Fort Lee?
Prince George, Petersburg, Colonial Heights, Hopewell, Chester and Dinwiddie are popular for short commutes to Fort Lee. Chesterfield and Midlothian are popular for Defense Supply Center Richmond and Richmond-area jobs.
Why work with a veteran-led real estate team?
Because we've lived the timelines, the PCS stress and the paperwork. One Dream Realty Group is led by Dustin Olverson, a 25-year U.S. Army veteran, and our team includes other veterans and military-connected agents. The team ranks #2 Mega Team in Richmond by sides and volume (RealTrends Verified 2026).
Sources
- VA: Eligibility requirements for VA home loan programs
- VA: Funding fee and closing costs
- VA: Loan limits and entitlement
- Code of Virginia § 58.1-3219.5: disabled veteran real estate tax exemption
- Code of Virginia § 58.1-322.02: military retirement and Guard pay subtractions
- U.S. Department of Justice: Servicemembers Civil Relief Act
- DoD: BAH rate lookup
This guide is general information, not legal, tax or lending advice. Your lender confirms eligibility, entitlement and fees. Tax rules can change; confirm with a tax professional or your locality.
Start Here
Thank you for your service
Call 804-720-1286 or book a 30-minute call (Thursdays and Fridays, 9–11am).
One Dream Realty Group · Brokered by eXp Realty. Not affiliated with or endorsed by the U.S. Department of Veterans Affairs.
Let's Connect If you want a newer community with real amenities and quick access to the whole Richmond area, Silverleaf in North Chesterfield should be on your list. I toured a home there and walked through what th...